Setting up a company in France is not just a matter of filling in a form. You are writing the rules your business will live by for years. The legal form you choose and the clauses in your articles of association decide how you are taxed, your social security status as a manager, your ability to bring in investors and the way decisions are made. The firm is based in Paris and acts throughout France.
Maître Léa Scemama, a company formation lawyer in Paris, advises entrepreneurs, executives and investors, whether they live in France or abroad, on setting up a company anywhere in France. She takes you from the choice of structure through to registration, and makes sure each decision serves your project rather than a standard template. See all our services in corporate law.
Instructing the firm to set up your company
| Your case | What the firm provides |
|---|---|
| Getting started | A call back within 24 working hours, then a first conversation, by video call if you are abroad, to understand your project, the number of shareholders, their contributions and your funding needs, and to choose the legal form. |
| Fees | Standard articles for an SAS or an SARL: €700 to €1,000 excluding VAT. Bespoke articles, with several shareholders or preference shares: €1,000 to €1,500 excluding VAT. Formalities included. Set out in a fee agreement signed before any work starts. |
| Timescale | In practice, one to three weeks for the articles, then a few working days for registration once a complete file has been lodged on the single online portal. |
| Throughout France and abroad | Companies set up anywhere in France, including for founders and groups based abroad: meetings by video call, work in English or French, fee agreement signed electronically. |
| Follow-up | One point of contact, Maître Léa Scemama, from choosing the legal form to registration, with updates in English. |
How we handle a company formation
| When | What we do | What you receive |
|---|---|---|
| Before you choose | We analyse your project, your personal assets and your social security position, and compare the legal forms available | A reasoned note setting out the tax and social security consequences of each option |
| Drafting | Bespoke articles: governance, voting majorities, shareholders joining and leaving, fifty-fifty deadlocks | Articles that deal with the situations templates ignore |
| Contributions | We classify, value and pay in the contributions, and appoint a contributions auditor (an independent valuer of assets brought into the company) where the law requires one | Share capital whose value cannot be challenged later |
| Formalities | Deposit of the capital, legal notice in a legal gazette, filing through the online one-stop portal, declaration of beneficial owners | A registered company, ready to sign contracts |
| First months | Statutory registers, first shareholder resolutions, a shareholders' agreement if there are several of you | A company that is in order from its first financial year |
How we bill is explained on our fees page.
Choosing the right legal form for your French company
The legal form is the first structural decision you take, and the one with the most consequences. SAS, SASU, SARL, EURL, SCI (a non-trading company often used to hold property), professional practice company: each follows its own logic on liability, tax, the social security status of the manager and governance.
In particular, the firm helps you choose between:
- The SAS, whose articles can be tailored almost freely and whose president is treated as an employee for social security purposes: a good fit for high-growth projects and for bringing in investors
- The SARL, a more protective framework in which a majority manager is self-employed for social security purposes, which often means lower social contributions
- The SCI, to hold and manage property with others or to plan how it will be passed on
- Single-member forms (SASU, EURL), for an entrepreneur on their own who wants to keep personal assets separate from those of the business
SAS or SARL: the six criteria that decide
| Criterion | SAS and SASU | SARL and EURL |
|---|---|---|
| Freedom to draft the articles | Very wide: the articles organise almost everything | Limited: the law sets the essentials |
| Head of the company | President, treated as an employee for social security | Manager, self-employed if a majority shareholder |
| Social security contributions of the head of the company | Higher, with cover in line with the general scheme for employees | Lower, with less cover and no unemployment insurance |
| Selling shares | Free unless the articles provide otherwise, registration duty of 0.1% | Approval required by law for sales to outsiders, duty of 3% after an allowance |
| Bringing in investors | Well suited: preference shares, share warrants, BSPCE (founder share warrants) | Poorly suited: securities cannot be offered to the public |
| Minimum capital | €1 | €1 |
Neither form is better in itself. The right choice depends on how much you plan to pay yourself, the social protection you have today and whether you expect investors within three years.
The mistakes that prove expensive
Most of the disputes between shareholders that we handle go back to articles drafted in a hurry when the company was formed. A corporate purpose so narrow that it blocks a new activity. No approval clause, so any outsider can buy into the company. A vague division of powers. No way out of a 50/50 deadlock. These flaws only come to light at the worst possible moment.
Getting the formation right costs far less than unwinding a dispute between shareholders a few years later.
Professional practice companies and holding companies: special cases
Two situations call for different articles from those of an ordinary trading company.
SELAS and SELARL: a company for a regulated profession
Doctors, lawyers, pharmacists and other regulated professions can practise through a professional practice company (SEL), most often in the form of an SELAS or an SELARL. Since 1 September 2024, the framework has been set by Ordinance No. 2023-77 of 8 February 2023 on practising regulated professions through companies.
The central rule concerns ownership: more than half of the share capital and voting rights must be held by professionals practising within the company, either directly or through a financial holding company of professionals (SPFPL) (article 46 of the Ordinance). Each profession adds its own rules, set by its legislation and its professional body, which govern in particular whether outside shareholders may come in.
An SELAS works like an SAS and an SELARL like an SARL. The choice turns on the same criteria as for a trading company, plus the constraints of the profession, which the firm checks before drafting the articles.
Setting up a holding company
A holding company is a company, often an SAS, that owns shares in one or more other companies. It is used to group investments together, to reinvest profits passed up from subsidiaries or to prepare a handover.
Whether it pays off depends almost entirely on the tax position in each case, in particular the parent and subsidiary regime or tax consolidation, whose conditions need to be checked case by case with your accountant. The firm structures the holding company, drafts its articles and, where relevant, the contribution of shares in existing companies.
Our fees for setting up a company, by legal form
| Legal form | Our fees |
|---|---|
| SAS or SASU, standard articles | €700 to €1,000 excluding VAT |
| SARL or EURL, standard articles | €700 to €1,000 excluding VAT |
| Bespoke articles, several shareholders or preference shares | €1,000 to €1,500 excluding VAT |
| SELAS or SELARL | Quote after the first conversation, depending on the rules of the profession |
| Holding company | Quote after the first conversation |
Formalities included. External costs (legal notice, court registry fees, contributions auditor where needed) come on top: see the table of costs below.
Drafting the articles: the heart of the matter
The articles of association are your company's constitution. A template downloaded online is enough to register a company, but it does not help when the first problem arises: a shareholder who wants to leave, a disagreement over a strategic decision, a new partner joining. Well-drafted articles deal with these situations in advance, instead of leaving you to cope with them when they happen.
The firm drafts bespoke articles that set out:
- The corporate purpose, duration and registered office, defined precisely enough not to restrict future activity
- Management rules: appointment, powers and removal of the president or manager
- How decisions are taken, and the majorities required for ordinary and extraordinary decisions
- How shareholders join and leave: approval, pre-emption rights, share transfers
- How profits are allocated and dividends distributed
Beyond the articles, as soon as there are several shareholders, a shareholders' agreement completes the picture. It governs, confidentially, the relationship between shareholders and the ways each of them can exit.
Contributions, share capital and paying it in
The share capital is made up of what the shareholders contribute. A contribution can be in cash, in kind (an asset such as equipment, a business, a building or intellectual property rights) or in skills (know-how, which does not count towards the capital but still entitles the contributor to shares). Each type of contribution follows its own rules.
Contributions in kind need particular care. The shareholders are liable for the value given to them and, above certain thresholds, a contributions auditor must step in. The firm checks how each contribution is classified, valued and paid in, so that nobody can dispute the value of the capital later.
When you can dispense with a contributions auditor
The exemption requires a unanimous decision of the future shareholders and two cumulative conditions: no single contribution in kind exceeds €30,000, and the total value of the contributions in kind not valued by an auditor does not exceed half of the share capital. It is available in an SARL as in an SAS (articles L. 223-9 and D. 223-6-1, L. 227-1 and D. 227-3 of the Commercial Code).
Doing without an auditor comes at a price: the shareholders are jointly and severally liable, for five years, for the value given to the contributions. Where the contribution is a business or intellectual property rights, the saving is rarely worth the risk.
Paying up the capital: what the law requires for each form
The minimum amount paid up on cash contributions depends on the legal form.
| SARL | SAS | |
|---|---|---|
| Minimum paid up on cash contributions at incorporation | One fifth | One half |
| Deadline for paying the balance | Five years from registration | Five years from registration |
| Legal basis | Article L. 223-7 of the Commercial Code | Articles L. 227-1 and L. 225-3 of the Commercial Code |
| Contributions in kind | Fully paid up on issue | Fully paid up on issue |
| Exemption from a contribution auditor | Article L. 223-9 | Article L. 227-1 |
| Example: capital of €50,000 in cash | €10,000 to pay at incorporation | €25,000 to pay at incorporation |
With capital of €50,000, the difference is €15,000 of cash you need on day one.
Registering the company: the formalities
Since 2023, every company formation goes through the online one-stop portal run by INPI, the French industrial property office. The steps are the deposit of the capital, publication of a formation notice in a legal gazette (a publication approved for official notices), filing of the registration application and the declaration of beneficial owners. Each one must be done in the right order and without errors. Otherwise the file is rejected and the start of your business is delayed.
The firm coordinates all of these formalities and hands over a registered company, with consistent articles and clear governance, ready to sign contracts and open its bank accounts. If your project means reorganising existing companies rather than creating a new one, see our restructuring and mergers page.
Two rulings of the Court of Cassation, France's highest court, to know before you sign
Commitments made before registration bind the people who signed them personally, until the company, once registered, takes them over (article L. 210-6 of the Commercial Code). Since a change in case law on 29 November 2023, a commitment that does not state that it is made in the name or on behalf of the company being formed is no longer rejected for that reason alone: the court looks at all the circumstances to establish what the parties actually intended (Cass. com., 29 November 2023, no. 22-12.865, published in the Bulletin). The company must still take the commitment over.
Another common belief is wrong: low share capital is not, in itself, a fault on the part of the director. If the contributions made on incorporation are insufficient, that is down to the shareholders, and it is not a management fault within the meaning of article L. 651-2 of the Commercial Code (Cass. com., 10 March 2015, no. 12-15.505, published in the Bulletin). Even so, the amount you choose sends a signal to banks and business partners.
Costs and timeframes for setting up a company
Typical figures for an SAS or an SARL set up with cash contributions. External costs are payable on top of our fees and vary with the legal form.
| Step | Costs to expect | Realistic timescale | Our fees |
|---|---|---|---|
| Choice of form and drafting of the articles | No external costs | In practice, one to three weeks, depending on the number of shareholders and how many drafts are exchanged | Standard articles for an SAS or an SARL: €700 to €1,000 excluding VAT. Bespoke articles, with several shareholders or preference shares: €1,000 to €1,500 excluding VAT |
| Deposit of the funds | Any charges made by the bank or institution holding the funds | In practice, a few days to obtain the certificate of deposit | Formalities included in the fee for the articles |
| Contributions in kind | The contributions auditor's fees, unless the shareholders dispense with an auditor under articles L. 223-9 and L. 227-1 of the Commercial Code | In practice, a few weeks for the auditor's report | Charged on time spent, at €300 excluding VAT per hour, for classifying the contributions and drafting the related documents |
| Legal notice of formation | Fixed fee, set according to the legal form | In practice, one to two days for publication | Formalities included |
| Registration and declaration of beneficial owners | Court registry fees for registration and for filing the declaration | In practice, a few working days once the file lodged on the online one-stop portal is complete | Formalities included |
External costs follow the official rates in force on the filing date. Where a contributions auditor is involved, they set their own fees.
Documents you will need to set up a company
The registration file must prove that the company has the right to use the premises of its registered office (article L. 123-11 of the Commercial Code), and it must include the declaration of beneficial owners (article L. 561-46 of the Monetary and Financial Code). Filing a complete file on day one avoids rejections.
- A valid identity document for each director and each individual shareholder
- For a corporate shareholder, a recent extract from its own company register and its articles, translated if they are in a foreign language
- Proof of the right to use the registered office: a lease, a title deed, a contract with a business domiciliation provider (a company that supplies a registered address) or a letter from the person hosting the company
- The director's sworn statement that they have no criminal conviction, and the names of their parents
- The certificate of deposit issued by the bank or institution holding the funds
- For a contribution in kind, the contributions auditor's report or the unanimous decision to dispense with one
- The list of beneficial owners, with the nature and extent of the control each one exercises
- Any contracts already signed on behalf of the company being formed, which the company will need to take over
Setting up a company: lawyer, accountant or online platform?
Three kinds of provider offer to set up your company. Their roles complement each other rather than compete: the chartered accountant keeps the books, the platform provides a form and the lawyer writes the rules between shareholders. Here is what each one can do, with the legal text that says so:
| Question | Chartered accountant | Online platform | Lawyer | Source |
|---|---|---|---|---|
| Drafting the articles | Only as a side activity, for a business whose accounts they already handle | Provides a template to fill in or a document generated from a questionnaire | Yes, this is the core of the job | Law of 31 December 1971, art. 54 and 59; Ordinance of 19 September 1945, art. 22 |
| Giving tailored legal advice, regularly and for a fee | Only where the advice is directly linked to their accounting work | Only if the operator meets the conditions laid down by law | Yes, in every field | Law of 31 December 1971, art. 54; Ordinance of 19 September 1945, art. 22 |
| Keeping the books and preparing the annual accounts | Yes, this is the profession | Depending on the platform's partners | No | Ordinance of 19 September 1945, art. 2 |
| Professional secrecy | Yes | Depending on the terms of use of the service | Yes, in all matters, advice included | Ordinance of 19 September 1945, art. 21; Law of 31 December 1971, art. 66-5 |
| Countersigning the deed | No | No | Yes: the lawyer certifies that they have fully advised the parties they act for, and the deed is then conclusive evidence of the parties' handwriting and signatures | Law of 31 December 1971, art. 66-3-1; Civil Code, art. 1374 |
| Lodging the file on the single online portal | Yes | Yes | Yes | Commercial Code, art. L. 123-33 |
You do not have to pick just one: many founders use a lawyer for the articles and an accountant for the books from the first financial year.
Online platforms set up companies quickly and cheaply, but they sell a form, not a strategy. A lawyer starts from your project, your assets and your plans, builds a structure around them and advises you independently, without selling you add-on services.
What a lawyer changes
Registering a company is a formality, and there are many ways to complete it. What we bring lies elsewhere, in the decisions that cannot be undone later:
- The choice of form, made in light of your personal assets, your current social security position and any investor you expect within three years, not only of the project as it stands today.
- The drafting of the clauses that matter on one day only, the day of disagreement: approval, pre-emption, departure of the director, resolution of fifty-fifty deadlocks. These are exactly the clauses a standard template does not contain, because they depend on your particular mix of shareholders.
- Advice covered by professional secrecy, which allows you to discuss foreseeable tensions between shareholders before they arise.
- The lawyer's professional liability for the advice given, covered by compulsory insurance.
The real question is therefore not the price of the formality, but the cost of the dispute that a missing clause will make possible. That is why we devote most of the work to the articles, not to the registration.
Once your company is up and running, the firm can assist you at every stage of its life: drafting the shareholders' agreement, fundraising rounds, share transfers or disputes between shareholders.
Setting up in France as a foreign company
A foreign group has two ways to start trading in France. A subsidiary is a French company, usually an SAS or an SARL, which becomes a legal person in its own right once registered (article 1842 of the Civil Code): it signs contracts and owes its debts in its own name. A branch has no legal personality of its own: it is an establishment of the foreign company, which is itself bound by what the branch does. The choice is first a question of liability, and only then of formalities.
The foreign parent can be the sole shareholder of an SAS and can itself be appointed president. Where a legal entity is appointed president of an SAS, its own managers are subject to the same conditions and obligations, and incur the same civil and criminal liability, as if they were president in their own name (article L. 227-7 of the Commercial Code).
The company must show, when applying for registration, that it has the use of the premises where it sets up its registered office (article L. 123-11 of the Commercial Code). A group with no premises yet can use a business domiciliation provider, a company that supplies a registered address and must hold an official approval to do so (article L. 123-11-3).
Every French company must obtain and keep accurate and up-to-date information on its beneficial owners and file it with the court registry (articles L. 561-45-1 and L. 561-46 of the Monetary and Financial Code). For a subsidiary, these are not the parent company but the individuals who ultimately hold, directly or indirectly, more than 25% of the capital or voting rights, or who otherwise control it (article R. 561-1). In practice, identifying them through several layers of holding companies is the step that most often holds up registration.
Setting up a French company: frequently asked questions
Do I need a lawyer to set up a company in France?
It is not compulsory, but it is strongly advisable once your project goes beyond a standard company with a single shareholder. A lawyer makes sure the legal form suits you, drafts articles tailored to your situation and deals in advance with the points of friction between shareholders that free templates ignore.
SAS or SARL: which should I choose?
An SAS gives you wide freedom to write your own articles, and its president is treated as an employee for social security purposes. An SARL is more tightly regulated by law, but can be the better option for a manager who holds the majority of the shares, who is then self-employed for social security purposes. The right choice depends on your project, on whether you plan to bring in investors and on your personal situation.
What is the minimum share capital for a French company?
The minimum capital is €1 for an SAS, an SASU, an SARL or an EURL (the single-member form of the SARL). Very low capital still sends a poor signal to banks and business partners, so the amount should match what the business actually needs.
How long does it take to set up a company in France?
Once the articles are finalised and the capital deposited, registration through the online one-stop portal run by INPI, the French industrial property office, generally takes a few days to two weeks. The decisive stage comes earlier: thinking through and drafting the articles, which should not be rushed.
Related topics
- Shareholders' agreement: what the articles cannot contain, settled privately between the shareholders.
- Sale of a business: buying an existing business instead of building a company from scratch.
- Commercial leases: the lease of your business premises, to negotiate before registration.
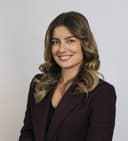
Written by Maître Léa Scemama, member of the Paris Bar, Miraï Avocats. This page sets out the law as it stood on the date it was last updated. It is general information, not advice on your particular situation.
Updated on